Expert Strategies for Minimizing Student Loan Debt with a 4-Year Plan Starting in 2026
Advertisements
Are you ready to face the massive shake-up hitting the federal student aid system? Mastering your Student Loan Debt 2026 planning is now more urgent than ever, especially with sweeping legislative reforms completely transforming how future graduates borrow and repay what they owe.
The complete overhaul of income-driven relief frameworks—such as the sun-setting of the SAVE program in favor of the strict new Repayment Assistance Plan (RAP)—means that passive financial management will cost you heavily.
New annual and lifetime borrowing limits, combined with the total elimination of Grad PLUS options for incoming scholars, have completely changed the rules of college financing.
We have mapped out an exclusive, expert-backed four-year roadmap tailored to these historic federal policy shifts.
Read on to discover how to navigate these strict new caps, qualify for vital interest-rate matches, and build a streamlined repayment strategy that completely protects your economic future.
Understanding the Evolving Student Loan Landscape for 2026
The student loan environment is poised for significant shifts by 2026, driven by economic factors and potential policy changes. Students entering higher education around this time must be acutely aware of these impending developments.
These changes could impact interest rates, repayment terms, and eligibility for various aid programs. Early preparation and informed decision-making will be crucial for minimizing future debt burdens.
Staying updated on legislative discussions and financial market trends is paramount for anyone planning to pursue higher education in the coming years. This proactive stance forms the bedrock of effective debt management.
Key Policy Forecasts and Their Impact
- Potential adjustments to federal student loan interest rates based on economic indicators.
- Revisions to income-driven repayment (IDR) plans, affecting monthly payments and forgiveness timelines.
- Changes in eligibility criteria for grants and scholarships, influencing upfront funding opportunities.
The federal government consistently reviews its student aid programs, often introducing new initiatives or modifying existing ones. These alterations can have profound implications for borrowing capacity and repayment obligations.
Students and their families should monitor announcements from the Department of Education and financial aid offices. These updates will provide critical insights into how to best structure their educational financing for the 2026 academic year.
Crafting a Strategic 4-Year Plan to Combat Student Loan Debt
A well-thought-out 4-year plan is the cornerstone of effective student loan debt minimization. This involves more than just applying for loans; it encompasses strategic academic, financial, and career planning from the outset.
This comprehensive approach ensures that every decision, from major selection to part-time employment, contributes to reducing overall borrowing. Such foresight can prevent unforeseen financial strain post-graduation.
Developing this plan early allows for flexibility and adjustments as circumstances change, providing a robust framework for financial resilience. It’s about making informed choices, not just reacting to immediate needs.
Year 1: Foundation and Early Decisions
- Focus on maximizing grants and scholarships to reduce initial loan dependency.
- Consider community college for initial credits to lower overall tuition costs.
- Establish a realistic budget for living expenses, including housing and textbooks.
The first year sets the trajectory for the entire college experience, financially speaking. Prioritizing free money over borrowed funds can significantly reduce the principal amount of student loan debt 2026 from the very beginning.
Exploring dual enrollment opportunities or AP credits can also shave off semesters, directly cutting down on tuition and associated borrowing. Every dollar saved in the early stages compounds into substantial savings later.
Maximizing Non-Loan Financial Aid Opportunities
Securing grants and scholarships is arguably the most impactful strategy for minimizing student loan debt 2026. These funds do not need to be repaid, directly reducing the amount a student must borrow.
The application process for these opportunities can be competitive and time-consuming, but the financial rewards are substantial. Many students overlook niche scholarships that perfectly match their unique profiles.
Dedicated effort in researching and applying for various non-loan aid sources should be a top priority for all prospective students. It is a critical component of any effective financial plan.
Unlocking Scholarship and Grant Potential
Students should begin their scholarship search well before college applications, often as early as junior year of high school. Utilizing online scholarship databases, school guidance counselors, and community organizations can uncover numerous opportunities.
Furthermore, many colleges offer institutional grants based on merit or financial need, which can be a significant portion of a student’s aid package. Understanding the specific requirements for these can be a game-changer.
Even after starting college, students should continue to seek out departmental scholarships or grants for specific majors or research projects. These ongoing efforts can further reduce the need for additional loans.
Strategic Borrowing and Loan Management
When loans become necessary, understanding the different types and their implications is vital for minimizing student loan debt 2026. Federal loans often offer more favorable terms and protections than private loans.
Subsidized federal loans, for instance, do not accrue interest while the student is in school, providing a significant advantage. Unsubsidized loans, while accruing interest, still offer more flexible repayment options than most private alternatives.
Borrowing only what is absolutely necessary, rather than the maximum offered, is a disciplined approach that pays dividends. Every dollar not borrowed is a dollar not repaid with interest.
Federal vs. Private Loans: A Critical Distinction
- Federal loans: generally offer fixed interest rates, income-driven repayment plans, and potential for forgiveness.
- Private loans: typically have variable interest rates, fewer repayment protections, and require a co-signer.
- Always exhaust federal loan options before considering private loans due to better terms and borrower protections.
Federal student loans come with a suite of borrower benefits, including deferment, forbearance, and various income-driven repayment plans, which can be lifelines during periods of financial hardship.
Private loans, while sometimes necessary, should be approached with extreme caution due to their often less flexible terms and higher interest rates. Comparing offers from multiple lenders is crucial if private financing is pursued.
Budgeting and Expense Control During College
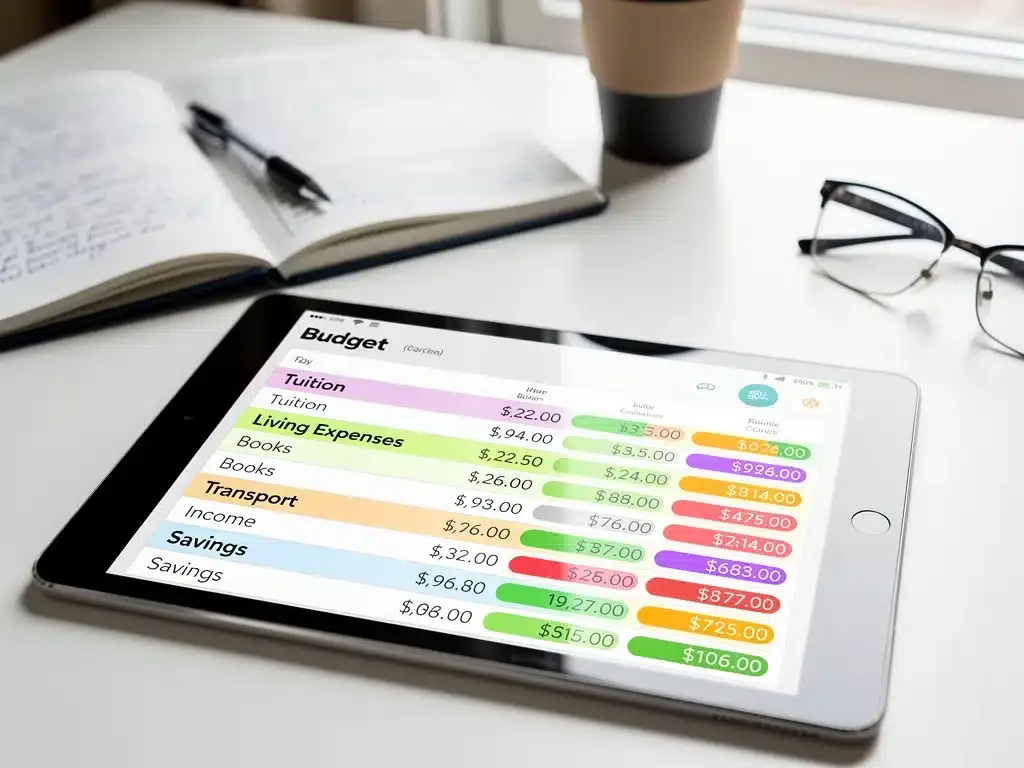
Effective budgeting throughout college is indispensable for minimizing student loan debt 2026. Managing daily expenses can prevent the need for additional borrowing for living costs.
Many students underestimate the cumulative impact of small, discretionary spending choices. A clear understanding of income and expenses empowers students to make financially responsible decisions.
Creating and adhering to a detailed budget not only saves money but also instills valuable financial habits that extend beyond college. It’s an investment in future financial literacy.
Practical Budgeting Tips for Students
Start by tracking all income sources, including financial aid disbursements, part-time job earnings, and parental contributions. Then, categorize all expenses, distinguishing between fixed costs like tuition and rent, and variable costs such as food and entertainment.
Utilize budgeting apps or simple spreadsheets to monitor spending in real-time and identify areas for reduction. Regularly review the budget to ensure it remains aligned with financial goals and current spending patterns.
Consider cooking at home more often, taking advantage of student discounts, and exploring cheaper transportation options. These small adjustments can add up to significant savings over four years, directly reducing the need for additional student loan debt 2026.
Exploring Alternative Income Streams and Cost-Saving Measures
Beyond traditional financial aid, students have various avenues to generate income and reduce educational costs. These proactive measures can significantly lower the reliance on student loan debt 2026.
Part-time jobs, internships, and even starting a small side hustle can provide much-needed funds. Every dollar earned is a dollar less borrowed, contributing directly to debt reduction.
Additionally, exploring cost-saving measures like living off-campus, utilizing open-source textbooks, or choosing a university with lower tuition rates can make a substantial difference. These choices demand careful consideration during the planning phase.
Leveraging Work-Study and Internships
- Federal Work-Study programs offer part-time jobs on campus, providing income that doesn’t count against financial aid eligibility.
- Paid internships offer valuable work experience and income, often leading to full-time employment post-graduation.
- Freelance work or starting a small online business can provide flexible income tailored to a student’s schedule.
Many universities offer work-study opportunities that not only provide income but also relevant experience that can enhance a resume. These positions are often flexible and designed to accommodate academic schedules.
Seeking out paid internships, especially in one’s field of study, offers a dual benefit: earning money and gaining professional experience. This can lead to better job prospects and higher starting salaries, making repayment easier.
Post-Graduation Repayment Strategies and Options
Even with the best planning, some student loan debt 2026 is often inevitable. Developing a robust post-graduation repayment strategy is crucial for managing this debt effectively and efficiently.
Understanding the various repayment plans, including income-driven options, and knowing when to consolidate or refinance can save thousands of dollars over the life of the loan. Proactivity in repayment is just as important as in borrowing.
Graduates should not wait until payments are due to explore their options; instead, they should begin planning their repayment approach several months before graduation. This ensures a smooth transition into repayment.
Navigating Repayment Plans and Loan Forgiveness
Federal student loans offer several repayment plans, including standard, graduated, extended, and various income-driven repayment (IDR) plans. IDR plans adjust monthly payments based on income and family size, potentially offering forgiveness after a certain number of years.
Public Service Loan Forgiveness (PSLF) is another significant program for graduates working in eligible public service jobs, offering forgiveness of the remaining balance after 120 qualifying monthly payments.
For private loans, refinancing can sometimes lead to lower interest rates, but it’s important to weigh the pros and cons, as refinancing federal loans into private ones means losing federal protections. Always research thoroughly and compare offers.
The Long-Term Impact of Early Financial Prudence
The decisions made today regarding student loan debt 2026 will reverberate for years, impacting financial freedom, career choices, and overall well-being. Early financial prudence sets a strong foundation.
Minimizing debt during college frees up future income for other financial goals, such as saving for a home, investing, or starting a family. It creates a powerful ripple effect of positive financial outcomes.
This proactive approach fosters a sense of control and reduces financial stress, allowing graduates to pursue their passions without the heavy burden of excessive debt. It’s an investment in a more secure and fulfilling future.
Building a Foundation for Financial Freedom
Graduates who emerge with minimal student loan debt 2026 are better positioned to achieve financial milestones faster. They have more disposable income to allocate towards savings and investments, accelerating wealth accumulation.
This financial agility can also provide greater flexibility in career choices, allowing individuals to pursue lower-paying but more fulfilling jobs or even venture into entrepreneurship without immediate financial pressure.
Ultimately, the expert strategies discussed for minimizing student loan debt provide a roadmap to not just manage debt, but to build a robust financial future. It’s about empowering students to make choices that serve their long-term aspirations.
| Key Strategy | Brief Description |
|---|---|
| Maximize Free Aid | Prioritize grants and scholarships to avoid borrowing for educational costs. |
| Smart Borrowing | Choose federal loans over private, and borrow only what is absolutely essential. |
| Strict Budgeting | Control college expenses through meticulous budgeting and expense tracking. |
| Post-Grad Plan | Develop an early repayment strategy, including income-driven options and potential forgiveness. |
Frequently Asked Questions About Student Loan Debt 2026
What are the primary changes expected for student loans by 2026?▼By 2026, students may see adjustments in federal interest rates, modifications to income-driven repayment plans, and altered eligibility for various grants. These changes stem from ongoing economic shifts and potential legislative actions, requiring proactive monitoring from students and families.
How can I maximize grants and scholarships to reduce my debt?▼Maximizing grants and scholarships involves starting your search early, utilizing online databases, and contacting school counselors. Apply for federal, state, institutional, and private scholarships. Persistent effort in this area significantly reduces the need for borrowed funds, directly impacting your student loan debt 2026.
Is it better to choose federal or private student loans?▼Generally, federal student loans are preferable due to their fixed interest rates, income-driven repayment options, and borrower protections. Private loans often have variable rates and fewer safeguards. Always exhaust federal options before considering private loans to minimize risks associated with student loan debt 2026.
What role does budgeting play in minimizing student loan debt?▼Budgeting is critical for controlling college expenses and preventing the need for additional loans for living costs. By tracking income and expenditures, students can identify areas for savings, reducing overall borrowing. This financial discipline is a core component of minimizing student loan debt 2026.
What should I do after graduation to manage my student loans?▼After graduation, understand your repayment options, including income-driven plans and potential loan forgiveness programs like PSLF. Consider loan consolidation or refinancing if beneficial, but carefully weigh the pros and cons. Proactive planning ensures effective management of your student loan debt 2026.
Looking Ahead
The landscape surrounding student loan debt 2026 demands continuous vigilance and strategic planning from prospective and current students.
The insights provided on expert strategies for minimizing student loan debt offer a robust framework for navigating these financial complexities. Staying informed about policy changes and economic indicators will be paramount.
As the academic years approach 2026, monitoring official announcements from the Department of Education and financial institutions will be crucial.
These updates will offer the most current information regarding loan terms, eligibility, and repayment options, directly influencing personal financial decisions.
Ultimately, a proactive and informed approach to managing educational finances is not merely about avoiding debt; it is about building a foundation for long-term financial security and freedom, ensuring that higher education remains an accessible and advantageous investment.