Claiming Social Security Benefits in 2026: New Rules and a Potential 3.2% COLA Increase
Advertisements
Claiming Social Security Benefits in 2026 is expected to look different as new rules and a potential 3.2% cost-of-living adjustment attract attention from retirees and future beneficiaries. These developments could directly influence monthly income and retirement planning decisions.
As benefit policies evolve, many Americans are evaluating when and how to apply in order to maximize their payments. Changes to eligibility requirements and annual adjustments may create new opportunities, and new considerations, for those approaching retirement.
This article explores the most important updates, what they could mean for beneficiaries, and the factors worth monitoring throughout 2026. Understanding these changes can help you make more informed decisions about your financial future.
Understanding the 2026 Social Security Landscape
The year 2026 is poised to bring significant adjustments to Social Security benefits, impacting millions of Americans planning their retirement.
These changes encompass potential rule modifications and a crucial cost-of-living adjustment (COLA) that will influence benefit amounts.
As individuals approach their retirement years, understanding these forthcoming shifts becomes paramount for effective financial planning.
The Social Security Administration (SSA) regularly evaluates its programs to ensure long-term solvency and adapt to economic realities.
The proposed 3.2% COLA increase, while not yet final, is a key component drawing considerable attention. It reflects ongoing inflationary pressures and the need to maintain the purchasing power of benefits for retirees.
Potential 3.2% COLA Increase: What It Means
A potential 3.2% COLA increase for 2026 signifies a substantial adjustment designed to counteract inflation and preserve the real value of Social Security benefits. This percentage is an estimate based on current economic projections and historical data.
The COLA is determined by the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Its primary purpose is to ensure that beneficiaries’ purchasing power is not eroded by rising living costs, a critical aspect for those relying on these funds.
While the official announcement typically occurs later in the year, preliminary forecasts provide a crucial window into potential benefit enhancements. For many retirees, this increase can significantly impact their monthly income and overall financial stability.
How COLA is Calculated and Announced
The Social Security Administration calculates the COLA based on the increase in the CPI-W from the third quarter of the previous year to the third quarter of the current year. If there is no increase, there is no COLA.
The official COLA announcement usually takes place in October, with the new rates becoming effective in December and reflected in January payments. This timeline allows beneficiaries and financial planners to prepare for the adjustments.
- CPI-W Data: The primary metric used for COLA calculation.
- Annual Review: Conducted by the SSA to assess economic changes.
- October Announcement: Official COLA figure released to the public.
- January Implementation: New benefit amounts take effect.
Monitoring economic indicators throughout the year is essential for anticipating the final COLA figure. For those planning on Claiming Social Security Benefits in 2026, this adjustment is a major factor in their income projections.
New Rules and Their Impact on Claiming Social Security Benefits in 2026
Beyond the COLA, new rules for Claiming Social Security Benefits in 2026 could introduce changes to eligibility, claiming strategies, and benefit calculations.
These modifications are often a response to demographic shifts and the long-term financial health of the Social Security trust funds.
While specific legislative changes are still subject to debate and approval, ongoing discussions within Congress and the SSA suggest potential adjustments. These could include alterations to the full retirement age (FRA), earnings limits, or even benefit formulas.
Such changes, if enacted, would necessitate a re-evaluation of retirement plans for many individuals. Staying informed about legislative developments is crucial for those preparing to claim their benefits.
Potential Changes to Full Retirement Age (FRA)
One area frequently discussed is a potential increase in the Full Retirement Age (FRA). Currently, the FRA for those born in 1960 or later is 67, but proposals sometimes suggest raising it further to ensure the program’s sustainability.
An elevated FRA would mean individuals would have to work longer to receive their full benefits or accept reduced benefits by claiming earlier. This could significantly alter retirement timelines and financial projections.
- Current FRA: 67 for those born in 1960 or later.
- Proposed Increases: Discussions around extending FRA to 68 or 69.
- Impact on Benefits: Claiming before FRA results in reduced benefits.
Understanding any potential shifts in the FRA is critical for anyone considering Claiming Social Security Benefits in 2026. Early retirement decisions could have long-lasting financial consequences under new age requirements.
Eligibility Requirements for 2026 Benefits
Eligibility for Social Security benefits remains largely tied to an individual’s work history and contributions to the system through payroll taxes. To qualify, most individuals need to accumulate 40 work credits, which equates to 10 years of employment.
Each year, the amount of earnings required to earn a work credit is adjusted. For 2026, this threshold will likely see a slight increase, reflecting wage growth and economic changes.
It is essential for prospective beneficiaries to review their earnings records periodically to ensure accuracy and confirm they meet the credit requirements. The SSA provides tools for this purpose, including online statements and benefit calculators.
Verifying Your Work Credits and Earnings Record
Accessing your Social Security statement online is the most efficient way to review your credited earnings and ensure accuracy. This statement provides a detailed breakdown of your work history and estimated future benefits.
Any discrepancies in your earnings record should be addressed promptly with the SSA, as they can affect your eligibility and the amount of your future benefits. Corrections might require submitting proof of earnings, such as W-2 forms or tax returns.
- Online Access: Create an account on the SSA website to view your statement.
- Annual Review: Check your earnings record for accuracy each year.
- Correcting Errors: Contact the SSA with documentation if discrepancies are found.
Ensuring your work credits are accurate is a fundamental step when preparing for Claiming Social Security Benefits in 2026. A complete and correct record guarantees that you receive all the benefits you are entitled to.
Optimizing Your Claiming Strategy for 2026
Choosing when to start Claiming Social Security Benefits in 2026 is a complex decision with long-term financial implications. Factors such as health, other retirement income, and family situation all play a role in determining the optimal claiming age.
While individuals can claim benefits as early as age 62, doing so results in a permanent reduction in monthly payments. Conversely, delaying benefits past the Full Retirement Age (up to age 70) can lead to significantly higher monthly payouts.
Financial advisors often recommend analyzing various scenarios to determine the best strategy tailored to individual circumstances. This often involves balancing immediate income needs against maximizing lifetime benefits.
Factors Influencing Claiming Age Decisions
Your health status is a major consideration; if you anticipate a shorter lifespan, claiming earlier might be beneficial. However, if you expect to live a long life, delaying benefits could provide a greater overall payout.
Spousal benefits and survivor benefits also factor into the decision, particularly for married couples. Coordinated claiming strategies can maximize benefits for both partners and provide financial security for the surviving spouse.
- Personal Health: Anticipated longevity influences the best claiming age.
- Other Income Sources: Pensions, 401(k)s, and savings impact immediate needs.
- Spousal and Survivor Benefits: Coordinated strategies can optimize family benefits.
For those preparing for Claiming Social Security Benefits in 2026, a thorough evaluation of these factors, possibly with professional guidance, is crucial for making an informed and financially sound decision.
Application Process and Documentation for 2026
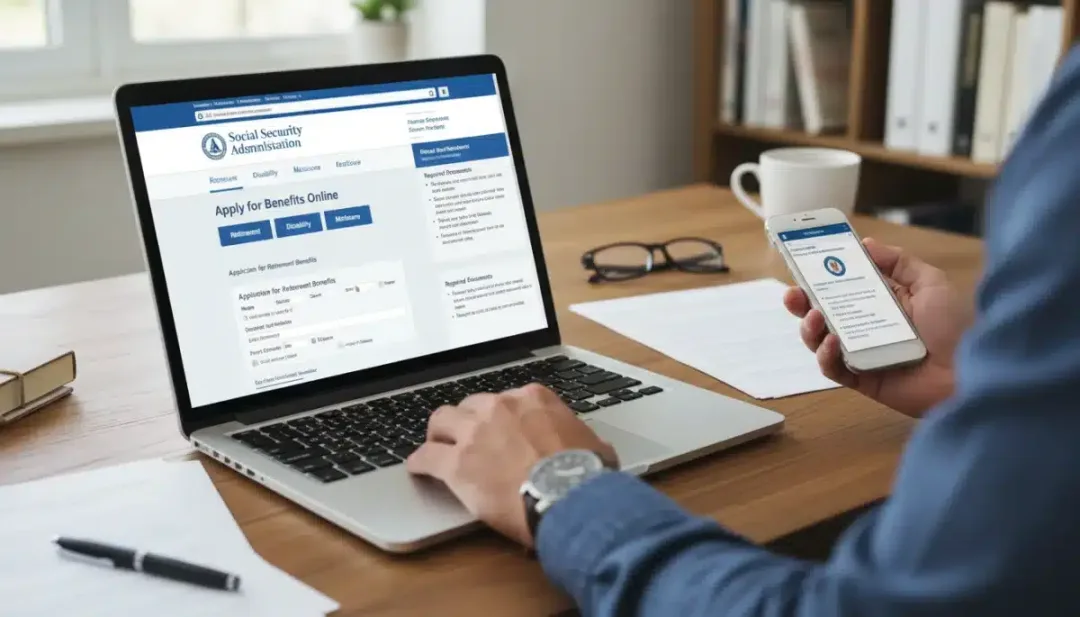
The application process for Social Security benefits can be initiated online, by phone, or in person at a local SSA office. It is generally recommended to apply several months before you wish your benefits to start.
Applicants will need to provide various documents, including proof of age, citizenship or legal alien status, and marriage certificates if applying for spousal benefits. Having these documents ready can significantly expedite the application process.
The SSA website offers comprehensive guides and checklists to help individuals gather the necessary paperwork. This ensures a smooth transition into receiving benefits and avoids unnecessary delays.
Essential Documents for Your Application
Before applying, gather your birth certificate or other proof of age, your Social Security card, and your most recent W-2 forms or self-employment tax returns. These are standard requirements for most applicants.
If you are applying for spousal or survivor benefits, you will also need marriage certificates and, in the case of survivor benefits, the death certificate of your spouse. Specific situations may require additional documentation, so it’s always best to check with the SSA.
- Proof of Age: Birth certificate or other acceptable document.
- Social Security Card: Your personal identification for the SSA.
- Earnings Records: W-2s or tax returns from recent years.
- Marriage/Death Certificates: For spousal or survivor benefits.
Preparing these documents in advance is a vital step for efficiently Claiming Social Security Benefits in 2026. A complete application package minimizes processing time and ensures timely receipt of your payments.
Staying Informed on Legislative and Economic Developments
The landscape of Social Security is dynamic, influenced by both legislative actions and broader economic trends. Staying informed about these developments is crucial for anyone planning on Claiming Social Security Benefits in 2026.
Congress periodically debates reforms to the Social Security system, which could lead to significant changes in benefit structures, taxation, or eligibility. These discussions are often driven by concerns about the program’s long-term solvency.
Economic indicators, such as inflation rates and wage growth, directly impact the COLA and could also influence legislative decisions. Monitoring these factors provides insight into potential future adjustments to your benefits.
Reliable Sources for Social Security Updates
The official Social Security Administration (SSA) website is the most authoritative source for information regarding benefits, rules, and updates. It provides direct access to announcements, policy changes, and personalized benefit statements.
Reputable financial news outlets and government publications also offer valuable insights and analysis on Social Security developments. These sources can help contextualize changes and provide expert opinions on their potential impact.
- SSA Website: Official announcements, policy changes, and FAQs.
- Congressional Records: Information on legislative proposals and debates.
- Economic Reports: Data on inflation and wage growth affecting COLA.
Proactively seeking information from these reliable sources will empower individuals to make well-informed decisions when Claiming Social Security Benefits in 2026. It ensures that your retirement planning is based on the most current and accurate data available.
Financial Planning Beyond Social Security Benefits
While Social Security provides a foundational income stream in retirement, it is rarely sufficient to cover all living expenses. Therefore, comprehensive financial planning extends well beyond just Claiming Social Security Benefits in 2026.
Developing a diversified retirement portfolio that includes personal savings, investments, and other income sources is critical. This multi-faceted approach helps build a robust financial safety net for your golden years.
Consulting with a financial advisor can provide personalized strategies for maximizing your retirement savings, managing investments, and planning for potential healthcare costs. This holistic view ensures greater financial security.
Building a Diversified Retirement Portfolio
Consider various investment vehicles such as 401(k)s, IRAs, and other taxable investment accounts. Diversification across different asset classes helps mitigate risk and enhance growth potential over the long term.
Budgeting for retirement expenses, including housing, healthcare, and leisure activities, is also essential. Understanding your anticipated costs allows you to determine how much income you will need beyond your Social Security benefits.
- Personal Savings: Augment Social Security with your own funds.
- Investment Accounts: Utilize 401(k)s, IRAs, and other platforms.
- Healthcare Planning: Account for rising medical costs in retirement.
A proactive approach to financial planning, encompassing strategies beyond just Claiming Social Security Benefits in 2026, is vital for achieving a comfortable and secure retirement. It provides peace of mind and greater control over your financial future.
| Key Point | Brief Description |
|---|---|
| Potential 3.2% COLA | Estimated Cost-of-Living Adjustment to maintain purchasing power. |
| New Rules Impact | Possible changes to eligibility, FRA, and claiming strategies. |
| Eligibility Verification | Ensure 40 work credits and accurate earnings record. |
| Optimal Claiming | Strategize claiming age based on health, other income, and family situation. |
Frequently Asked Questions About 2026 Social Security Benefits
What is the anticipated COLA for Social Security benefits in 2026?▼Current projections indicate a potential 3.2% Cost-of-Living Adjustment (COLA) for Social Security benefits in 2026. This estimate is based on economic forecasts and the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W), though the final figure will be officially announced later in the year.
Will there be changes to the Full Retirement Age for those Claiming Social Security Benefits in 2026?▼Discussions are ongoing regarding potential adjustments to the Full Retirement Age (FRA) as part of broader Social Security reforms. While no definitive changes have been enacted for 2026, individuals should monitor legislative developments, as any increase would affect claiming strategies and benefit amounts for future retirees.
How can I ensure I am eligible for Social Security benefits in 2026?▼To ensure eligibility, you generally need 40 work credits, accumulated through employment over at least 10 years. Regularly check your Social Security statement on the SSA website to verify your credited earnings and address any discrepancies, ensuring your record is accurate for Claiming Social Security Benefits in 2026.
When is the best time to apply for Social Security benefits in 2026?▼It is advisable to apply for Social Security benefits several months before you intend for your payments to begin. This allows ample time for processing and ensures you receive your benefits without interruption. You can apply online, by phone, or in person at an SSA office.
What documents are required for Claiming Social Security Benefits in 2026?▼Essential documents typically include your birth certificate, Social Security card, and recent W-2 forms or self-employment tax returns. For spousal or survivor benefits, marriage and death certificates may also be required. A complete list is available on the official Social Security Administration website.
Looking Ahead: Preparing for Your 2026 Benefits
The evolving landscape surrounding Claiming Social Security Benefits in 2026, including potential new rules and the estimated 3.2% COLA, underscores the importance of proactive planning.
Staying informed through official channels and reviewing your personal Social Security statement are critical first steps.
As legislative discussions continue and economic data refines COLA projections, future retirees must adapt their strategies.
This ongoing vigilance ensures that individuals can optimize their claiming decisions and integrate Social Security effectively into their broader financial retirement plans.
The journey to Claiming Social Security Benefits in 2026 requires careful consideration and continuous engagement with updated information, empowering beneficiaries to secure their financial future amidst inevitable changes.